Key headlines1
- Strategic actions to accelerate customer wins delivering results
- Volume-led revenue growth +1% with volume/mix +3%
- Solutions new business wins by value up 15ppts at 58%; revenue from New Products +4%2
- EBITDA (8)% in-line with management’s expectations
- US$200 million 5-year productivity programme on track with further US$27m savings delivered in H1
- Free cash flow of £100m with cash conversion of 75% in-line with guidance (2025 – 71%)
- Interim dividend increased by 0.2p to 6.8p per share in-line with Rule 2.7 announcement in June
- Consolidation of capacity for bio-gums production progressing as planned
- Outlook for the 2027 financial year maintained
Offer for the company
The scheme of arrangement for the recommended acquisition of Tate & Lyle by Ingredion Incorporated was approved by Tate & Lyle's shareholders on 28 July 2026 with 98.64% of votes cast in favour.
Regulatory and antitrust filings are in progress and we continue to expect completion in the second half of the 2027 calendar year.
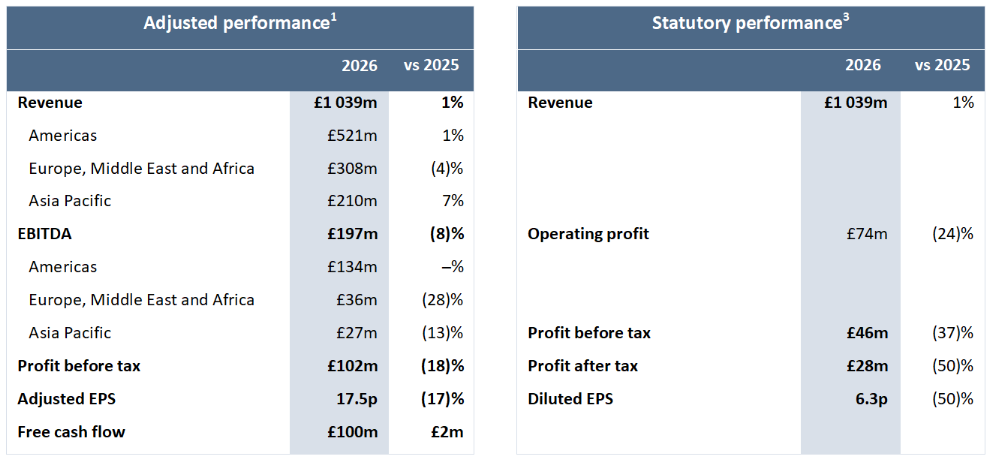
Financial summary
Nick Hampton, Chief Executive, Tate & Lyle said:
“The Group performed well in the first half with a return to top-line growth and profit in line with our expectations. We delivered strong top-line momentum in Asia Pacific and a robust performance in the Americas which together helped to offset a more challenging environment in Europe, Middle East and Africa.
The actions we’ve taken over the last year to strengthen our customer-facing capabilities, insights and tools to accelerate customer wins, drive commercial excellence across the business and to support volume-led top-line growth are making a tangible impact. Customer engagement is increasing and this is turning the strength of our new business pipeline into volume-led growth. Overall, I am encouraged by our performance in the first half which reflects the strength of our portfolio, the deep technical expertise of our people, and the power of the CP Kelco combination. I want to thank all my colleagues for their continued passion and commitment to deliver on our priorities in what is a period of significant change for the Company.
Looking ahead, as we continue to operate in a challenging inflationary environment, we remain focused on what we can control – on continued strategic execution, driving top-line growth, maintaining cost discipline and delivering for our customers.”
Outlook
The outlook for the year ending 31 March 2027 is maintained. On a constant currency basis, we expect to deliver:
- Modest revenue growth, underpinned by volume growth, weighted to the second half
- Broadly flat EBITDA before the c.US$20 million impact of the rescheduling of the consolidation of bio-gums capacity.
The extension of the conflict in the Middle East means that the impact has become more pronounced than originally anticipated and we intend to pass through cost inflation as we renew customer framework agreements for the 2027 calendar year while also seeking to offset cost inflation through a range of initiatives including procurement activities and operational discipline.
Financial highlights
Overview
- Group revenue4 +1% (+2% excluding bulk sweeteners/co-products in Europe and tariff reimbursements in US)
- Group adjusted EBITDA4 (8)% lower
- Adjusted EBITDA margin4 (190)bps lower at 19.0%
- Adjusted profit before tax4 (18)% lower at £102m
- Statutory profit before tax (37)% lower at £46m
- Statutory diluted EPS at 6.3p, (50)% lower
- Productivity savings of US$27m delivered in H1
- Return on capital employed5 decreased by (50)bps to 7.7%.
Strong balance sheet
- Free cash flow5 of £100m, £2m higher with cash conversion of 75%
- Net debt5 £959m at 30 September 2026, £20m higher than at 31 March 2026
- Net debt to EBITDA leverage5 2.3 times on a covenant basis6 (2025 – 2.4 times); 2.4 times on reported basis
- Interim dividend increased by 0.2p to 6.8p per share.
Results presentation and webcast
A pre-recorded video presentation of the results for the six months to 30 September 2026 by Chief Executive, Nick Hampton, and Chief Financial Officer, Sarah Kuijlaars is available via the Results and Presentations page of the Company’s website.
Management will host a live audio Q&A session via a conference call today at 09:00 GMT. Participants are requested to dial in at least 10 minutes before the commencement of the call. Dial-in details are as follows:
UK: +44 (0) 33 0551 0200
UK Toll Free: 0808 109 0700
USA Toll Free: 866 580 3963
Password: Tate & Lyle
The archived version of the presentation including Q&A will be available via the Results and Presentations page by 12:00 GMT.
For more information contact Tate & Lyle PLC:
Kate Postans, VP Investor Relations
Tel: Mobile: +44 (0) 7388 702 934
Nick Hasell, FTI Consulting (Media)
Tel: Mobile: +44 (0) 7825 523 383
Tel: Office: +44 (0) 203 727 1340 [email protected]
Cautionary statement
This statement of half-year results for the six months to 30 September 2026 (Statement) contains certain forward-looking statements with respect to the financial condition, results, operations and businesses of Tate & Lyle PLC. These statements and forecasts involve risk and uncertainty because they relate to events and depend upon circumstances that will occur in the future. There are a number of factors that could cause actual results or developments to differ materially from those expressed or implied by these forward-looking statements and forecasts.
A copy of this Statement can be found on our website at www.tateandlyle.com. A hard copy is also available from the Company Secretary, Tate & Lyle PLC, 5 Marble Arch, London W1H 7EJ.
1. Revenue growth, adjusted EBITDA and adjusted EBITDA margin, adjusted earnings per share, free cash flow, return on capital employed, net debt and net debt to EBITDA are non-GAAP measures (see pages 8 to 11). Changes in adjusted performance metrics are in constant currency.
2. New Products revenue on a like-for-like basis (i.e. no products removed from disclosure due to age); revenue was (5)% on a reported basis in constant currency.
3. Statutory performance metrics changes are in reported currency.
4. Changes in constant currency.
5. Non-GAAP measures (see pages 8 to 11).
6. Covenant basis principally excludes the impact of leases and translates net debt at average rates; reported basis includes leases.